TL;DR

Turn your wind-down time into listening time
- Thousands of audiobooks, podcasts and originals
- Listen on your phone, tablet or Echo — also offline
- Cancel anytime
A Sixty and Me report outlines six steps for people facing divorce near retirement: understand state law, increase savings, build an independent plan, consult a financial planner, review healthcare and consider downsizing. The article offers guidance rather than new research, and its statistics do not include enough detail to verify their underlying sources.
Sixty and Me has published six financial planning suggestions for people facing divorce near retirement, including seeking legal and financial advice, reviewing healthcare coverage and adjusting housing or spending. The article focuses on the financial pressures that can follow a later-life split, particularly for women, but presents guidance rather than reporting a new policy, study or change in law.
The article recommends that readers learn the divorce laws in their state and consult a lawyer about how assets may be divided, especially if there is no prenuptial agreement. It notes that rules vary by state and cautions against assuming a particular division applies without legal advice. The report does not provide state-by-state legal information.
Its other suggestions are to save more where possible, develop an independent retirement plan, and work with a financial planner to assess income, savings and future expenses. It also urges readers to check whether they can retain or replace health coverage after a divorce. The article says eligibility depends on the policy and applicable rules, but does not identify a specific coverage pathway.
The sixth suggestion is to consider downsizing or reducing expenses, such as moving to a smaller home or choosing a less costly vehicle. The report frames these as choices to weigh against personal priorities, including travel, rather than as measures that will suit everyone. It does not estimate how much any step might save or how much additional income a newly single retiree may need.
Planning for a Single Retirement
Divorce close to retirement can change the financial picture from shared income and expenses to a household managed on one person’s resources. That can affect housing decisions, savings targets, insurance arrangements and the timing of retirement. The article’s advice matters because these choices can be connected: a change in housing costs, for example, may alter how much a person can save or spend elsewhere.
The report gives particular attention to women’s financial risks, citing longer average life expectancy, time spent away from paid work for caregiving and the possibility that a spouse handled household finances. These are general concerns raised by the article, not a finding about every woman or every divorce. Individual circumstances, assets, benefit histories and local law vary.
Products Worth Considering

LEVOIT Vital 200S-P Smart Air Purifier for Large Rooms up to 1875 ft², Quiet 27 dB Operation, AHAM VERIFIDE Certified, Air Quality Monitor,

Blueair Blue Pure 511i Max Smart Air Purifier
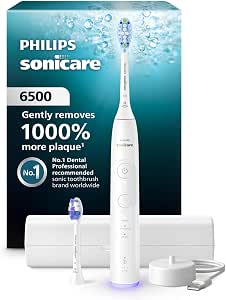
Philips Sonicare 6500 Series Rechargeable Electric Toothbrush with 2 Brush Heads, White
As an affiliate, we earn on qualifying purchases.
What the Article Cites
The source says studies have found that the number of people over 50 who divorced nearly doubled from 1990 to 2010, and says researchers use “gray divorce” for divorces among people over 55. It does not name the studies or provide their methods, so the figure should be understood as a statistic cited by the article, not independently verified here.
The report also states that 24% of Baby Boomers felt they had saved enough for retirement, describing that figure as 12% lower than five years earlier. It does not identify the survey, field dates, sample or whether the 12% refers to a percentage-point change or a relative decline. The source further says one in three Baby Boomers is single at retirement age, without giving a date or definition of “single.”
““Take Control of Your Own Future.””
— Sixty and Me
Details Readers Should Verify
The article does not specify when it was published or link, in the supplied material, to the studies behind its demographic and savings statistics. Their current relevance and the basis for the reported comparisons are therefore unclear. Readers should not treat those figures as a forecast for an individual household.
Legal outcomes and access to health coverage depend on a person’s location, finances, policy terms and other details. The article does not establish what assets a reader would receive, whether coverage could continue, or what retirement income would be sufficient. Those questions require advice based on the person’s circumstances.
Steps Before Financial Decisions
The report offers no announced follow-up or policy milestone. For readers considering divorce, its practical next steps are to gather financial records, learn which state rules apply, and discuss asset division with a qualified lawyer. A financial planner can help map income, savings and expenses under different retirement scenarios.
Readers should also contact their insurer or relevant benefits administrator to ask about coverage after divorce, then compare housing and spending options against their needs. The article’s central point is preparation; it does not promise that any single step will prevent financial strain or produce a particular outcome.
Key Questions
What are the six suggestions in the report?
It recommends learning applicable divorce law, saving more, making an independent retirement plan, working with a financial planner, reviewing healthcare coverage and considering downsizing or other spending changes.
Does the article say how assets will be divided?
No. It says divorce law varies by state and advises consulting a lawyer. It does not determine how a particular couple’s property would be divided.
Can someone keep a former spouse’s health insurance after divorce?
The source does not give a universal answer. It says coverage depends on the insurance policy and applicable rules, so readers need to check their own plan and circumstances.
Are the statistics in the article independently verified?
The supplied report text does not identify the studies or survey behind its figures. Their methods, dates and comparison basis are not available here.
Source: sixtyandme.com